Quick answer: Section 43B(h) denies a buyer its income-tax deduction for money owed to a micro or small enterprise until it actually pays. The payment limit is 45 days under a written agreement and 15 days without one. From 1 April 2026, Section 37(2)(g) of the Income-tax Act, 2025 carries the same rule.
Section 43B(h) MSME payment rules now shape how Indian businesses treat their small suppliers. The clause turns late payment into a tax cost. A buyer that holds back an invoice from a micro or small vendor loses the deduction for that expense until the cash leaves its account. This guide explains the rule, the 15-day and 45-day limits and the move to the new Income-tax Act. It also shows what a supplier can do with it, why the tax rule does not recover your money and which legal remedy does.
What this guide covers
- What Section 43B(h) says and where it now sits
- The 15-day and 45-day limits
- Who is protected and who is not
- When the clock starts
- Tax and MSMED Act consequences side by side
- Key judgments and open questions
- Step-by-step: use the rule to get paid
- How startups can benefit under the MSME Act
- Common mistakes
- FAQ
What Section 43B(h) says and where it now sits
Parliament inserted clause (h) into Section 43B of the Income-tax Act, 1961 through the Finance Act, 2023, effective from assessment year 2024-25. It covers any sum a buyer owes to a micro or small enterprise. If the buyer pays beyond the time limit in Section 15 of the Micro, Small and Medium Enterprises Development (MSMED) Act, 2006, the buyer gets the deduction only in the year of actual payment.
The Income-tax Act, 2025 took effect on 1 April 2026. Its Section 37(2)(g) now covers the same subject. Tax commentary says financial year 2025-26 still runs under the 1961 Act. Buyers will therefore cite Section 43B(h) in 2025-26 audits and Section 37(2)(g) from tax year 2026-27. Portals that reproduce the new text show that the grace period for paying before the return due date does not apply to this clause. Your accountant should confirm the section number against the official gazette.
The provision does not create a payment right. It only changes when the buyer can claim the cost. That distinction matters when you plan recovery.
The 15-day and 45-day limits
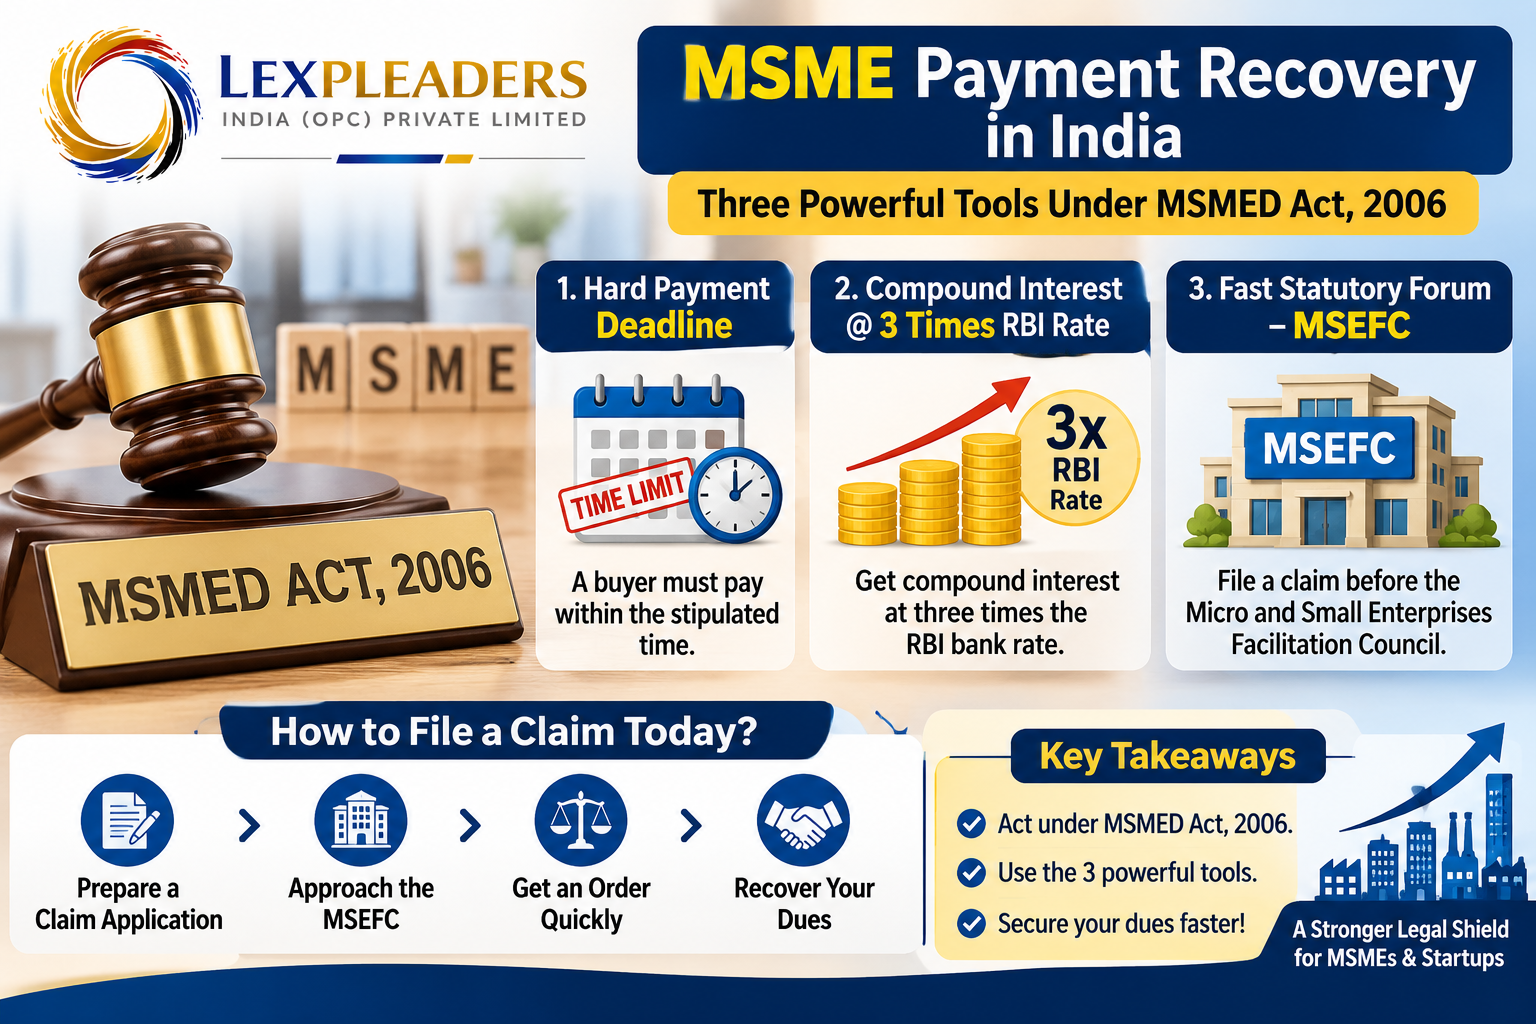
Section 15 of the MSMED Act sets the payment deadline. The buyer must pay on or before the date the parties agree in writing. That date cannot be more than 45 days after the day of acceptance. If no written agreement exists, the buyer must pay within 15 days of acceptance.
| Situation | Payment limit | Tax effect if late |
|---|---|---|
| No written agreement | 15 days from acceptance | Deduction waits until actual payment |
| Written agreement, 30-day credit | 30 days | Deduction waits if paid after day 30 |
| Written agreement, 90-day credit | Capped at 45 days | Deduction waits if paid after day 45 |
| Payment made within the limit | Within 15 or 45 days | Normal deduction on accrual |
A 90-day clause in a vendor contract does not override the statutory ceiling. Courts have held that the MSMED Act prevails over contrary private terms, and our guide on interest on delayed payment to MSME explains the Supreme Court ruling in Gujarat State Civil Supplies Corporation v Mahakali Foods (31 October 2022).
Who is protected and who is not
The clause protects micro and small enterprises. It names no medium enterprises, so dues to a medium supplier do not trigger it. Practitioner sources report that the supplier’s Udyam certificate decides its category. They also say a supplier registered mid-year gets cover only for supplies after its registration date.
| Category | Investment limit | Turnover limit | Covered by 43B(h)? |
|---|---|---|---|
| Micro | Up to Rs 2.5 crore | Up to Rs 10 crore | Yes |
| Small | Up to Rs 25 crore | Up to Rs 100 crore | Yes |
| Medium | Up to Rs 125 crore | Up to Rs 500 crore | No |
These limits apply from 1 April 2025. Two practical questions often arise. First, tax commentary says wholesale and retail traders generally fall outside the clause, because their Udyam registration serves priority-sector lending. Second, service providers do fall within it if they qualify as micro or small. Treat the trader point as a position to confirm with a chartered accountant, not as settled law.
When the clock starts
The 15-day and 45-day periods run from the day of acceptance or deemed acceptance. Under the Explanation to Section 15, acceptance generally means the day of actual delivery of goods or rendering of services. A written objection within the permitted window moves the clock to the day the objection ends. The law treats a silent buyer as having accepted.
This rule gives suppliers a simple habit. Keep the delivery challan, the lorry receipt, the signed acknowledgement and every email. A buyer that raises a late or oral objection has not stopped the clock.
Tax and MSMED Act consequences side by side
| Consequence | Source | Who it affects |
|---|---|---|
| Deduction deferred until payment | Section 43B(h) / Section 37(2)(g) | Buyer |
| Compound interest at three times the Bank Rate, monthly rests | Section 16 MSMED Act | Buyer pays, supplier receives |
| No tax deduction for that interest | Section 23 MSMED Act | Buyer |
| Disclosure of dues in tax audit report (Form 3CD, Clause 22) | Tax audit rules | Buyer and its auditor |
| Reference to the Facilitation Council | Section 18 MSMED Act | Supplier |
Interest is the real money. The RBI raised the repo rate to 5.50% on 7 October 2026 and set the Bank Rate at 5.75%. Three times that figure is 17.25% a year, compounded with monthly rests. The next Monetary Policy Committee meeting runs from 2 to 4 December 2026, so confirm the rate on the day you issue your notice. Our complete guide to MSME payment recovery walks through the interest calculation and the filing process.
Key judgments and open questions
Section 43B(h) has produced little reported case law so far. The disputes that matter for suppliers concern who counts as an MSME and from when.
- Silpi Industries v Kerala State Road Transport Corporation (Supreme Court, 2021): The Court tied the Chapter V benefits to registration, and later courts read it as requiring registration before the contract or supply.
- Gujarat State Civil Supplies Corporation v Mahakali Foods (Supreme Court, 31 October 2022): The Court held that the MSMED Act overrides private agreements and that the Council can act despite an arbitration clause.
- NBCC (India) Ltd v State of West Bengal (2025 INSC 54, Supreme Court, 10 January 2025): A two-judge bench held that an unregistered enterprise could use Section 18, found Silpi and Mahakali did not decide that point, and referred the issue to a larger bench. We could not confirm from retrieved sources that the larger bench has decided it.
- Shri Krishan Grit Co v Continental Engineering Corporation (Delhi High Court, 8 September 2026): A secondary report says Justice Tushar Rao Gedela held that MSMED benefits attach only to claims arising after registration. Read the judgment before you rely on it.
For the pre-deposit that a losing buyer must make before it challenges a Council award, see our note on Section 19 MSMED Act pre-deposit.
Step-by-step: use the rule to get paid
- Confirm that your Udyam certificate shows micro or small status on the date of the contract.
- Collect proof of delivery or completion and note the date of acceptance.
- Check whether a written agreement fixes the payment date, and cap it at 45 days.
- Send a written reminder that cites Section 15, the interest under Section 16 and the tax effect on the buyer.
- Issue a formal legal notice with a statement of interest if the buyer still delays. Our guide to legal notices in India explains the format.
- File on the MSME ODR portal (odr.msme.gov.in), which replaced MSME Samadhaan for new delayed-payment references from 15 October 2025.
- Choose a parallel civil route when the claim falls outside the Act, such as a summary suit under Order XXXVII CPC, arbitration or an insolvency demand.
How startups can benefit under the MSME Act
Startups sit on both sides of this rule. As a supplier, a registered micro or small startup can use the 45-day limit and the tax pressure in its contracts and renewals. Add a payment clause that states the due date and the Section 16 interest. As a buyer, a startup should pay MSME vendors within the limit, because late payment costs the deduction and adds non-deductible interest. Map every vendor against the Udyam portal, diarise due dates, and keep acceptance records. Our startup legal checklist covers the wider compliance picture.
Common mistakes
- Treating Section 43B(h) as a recovery remedy. It is a tax rule that only the buyer feels.
- Assuming a 60-day or 90-day contract term overrides the 45-day ceiling.
- Counting days from the invoice date instead of the acceptance date.
- Ignoring the Udyam registration date and certificate category.
- Assuming a part payment protects the whole invoice.
- Accepting a medium-enterprise supplier into the same payment process as a small one.
- Waiting beyond the three-year limitation period for a civil claim.
FAQ
What is the Section 43B(h) 45-day rule for MSME payments?
A buyer must pay a micro or small enterprise within the agreed period, which cannot exceed 45 days, or within 15 days if there is no written agreement. If it pays late, it can claim the expense as a tax deduction only in the year it actually pays.
Does Section 43B(h) apply to medium enterprises?
No. The clause names micro and small enterprises only, so dues to a medium enterprise fall outside it. Tax commentary and a CBDT FAQ reported by practitioners say the supplier’s Udyam certificate fixes its category.
What replaced Section 43B(h) under the Income-tax Act, 2025?
Section 37(2)(g) of the Income-tax Act, 2025 now carries the rule for tax years starting 1 April 2026. It repeats the same idea: a payment beyond the Section 15 time limit gets a deduction only when the buyer actually pays.
Is interest to an MSME supplier tax deductible?
No. Section 23 of the MSMED Act bars the buyer from deducting the compound interest it owes under Section 16 when it computes its income. That rule applies on top of the Section 43B(h) deferral.
Can a supplier sue under Section 43B(h)?
No. Section 43B(h) is a tax provision, and a supplier cannot enforce it in court. A supplier recovers its dues through the MSMED Act, a summary suit, arbitration or an insolvency notice, and uses the tax rule as pressure on the buyer.
When does the 45-day clock start?
The clock starts on the day of acceptance or deemed acceptance of the goods or services, not on the invoice date. A buyer who objects in writing within the permitted window can move the start date, so suppliers should keep proof of delivery.
Sources and references
- RBI Monetary Policy Statement, 7 October 2026 (repo rate 5.50%, Bank Rate 5.75%)
- Section 37, Income-tax Act, 2025 (statute text as reproduced by eztax.in)
- TaxUpdate: Section 43B and 43B(h) under the Income-tax Act 2025
- TaxGuru: 15/45-day rule and Form 3CD Clause 22
- Verdictum: NBCC (India) Ltd v State of West Bengal, 2025 INSC 54
- Sansa Legal: Delhi High Court on prospective MSME registration
Last updated: 8 November 2026
Talk to a lawyer about your unpaid dues
Lex Pleaders advises MSMEs, startups, banks, NBFCs and businesses on recovery of dues and commercial disputes. WhatsApp or call 8595333579 (https://wa.me/918595333579) or write to lexpleadersindia@gmail.com to discuss your matter. Our chamber is at Chamber No. 209, C.K. Daphtary Block, Supreme Court of India, New Delhi – 110001. We work as a law firm in Delhi NCR with matters before courts, tribunals and arbitral panels.
Disclaimer: This article offers general information only and does not constitute legal advice.